

1. The core advantages of Hong Kong S88 recognized charity application
Institutional tax-exempt status
Profits tax exemption (subject to strict conditions),Significantly reduce operating costs,Align more resources to charitable purposes。
Donation tax deduction certificate
The donor makes a pure monetary donation of not less than HK$100 to your organization,You can apply for salary tax with receipts、Deductions from profits tax or personal assessment,Significantly increase the appeal of fundraising。
Other tax exemptions
Article 88 Confirmation mainly relates to qualifying tax status;Business registration、Whether stamp duty and other taxes or government charges are exempted or reduced,Must be based on the legal form of the organization、Check transactions and current legislation separately,No automatic deduction can be made from Article 88 confirmation。
Enhance credibility
The Inland Revenue Department provides official inquiries and lists of section 88 charities and charitable trusts,Available for verification by donors and the public。Listing helps fact-checking,But don’t promise to necessarily increase fundraising、Funding or collaboration results。
2. Hong Kong S88 Charitable purpose categories applied by recognized charitable organizations
| category | Description and examples | geographical restrictions |
|---|---|---|
| 1. Poverty relief | Providing food to the financially disadvantaged、residence、Basic necessities such as medical care。 | Unlimited |
| 2. promote education | set up school、scholarships available、Funding research、Knowledge and skills training。 | Unlimited |
| 3. promote religion | Build churches and temples、Support religious activities,Must be of public nature。 | Unlimited |
| 4. Other charitable purposes that benefit Hong Kong society | Help the sick、protect the environment、Promote health、Prevent animal cruelty, etc.。 | Must be beneficial to Hong Kong society |

3. Comparison of legal structures for applications by Hong Kong S88 recognized charities
| legal structure | regulatory instruments | Check the key points |
|---|---|---|
| company limited by guarantee | Articles of Association | Member liability is limited to the amount of guarantee,and must also comply with company law、Reporting and governance requirements;The tax office does not list it as a unified "first choice" for all applications。 |
| Societies | emblem | Member responsibilities must be confirmed in accordance with the Societies Ordinance and actual organizational arrangements、Asset holding and governance。 |
| trust | trust deed | powers of trustee、responsibility、Asset utilization and charitable purposes are confirmed in accordance with the trust deed and applicable laws.。 |
4. Application process for Hong Kong S88 recognized charity application
Step 1:Examine the purpose - pass the "four major charitable purposes" test
Your organization must be established solely for statutory charitable purposes。Cannot have any non-charitable purpose。Need to meet poverty relief、promote education、To promote religion or other charitable purposes that are beneficial to Hong Kong society。
Step 2:Choose a legal structure that matches your activities and governance
The institution must be established by written regulatory instruments。Companies limited by guarantee are widely used by charities because of their clearer governance and liability structures.,But the community、Trusts and other qualifying structures must also be assessed on a case-by-case basis。
Step 3:Draft regulatory instruments consistent with actual activities
Regulatory instruments should clearly state the charitable purpose、Purpose of funds and income、Member Benefits and Compensation Limitations、conflict of interest、Governance and post-dissolution asset arrangements,and consistent with the actual activities of the organization。
Step 4:Prepare a complete application package
Prepare establishment documents according to the current forms and checklists of the Inland Revenue Department、regulatory instruments、Governing Organization Information、Records of activities carried out or plans for future activities、Financial information and funding source description。Omissions or inconsistencies often trigger inquiries or fill-ins。
Step 5:Submit application to tax office
Submit the application according to the current submission method announced by the tax bureau。The tax bureau will review the case on a case-by-case basis,and may for the purpose、Activity、finance、Inquiries raised by governance or regulatory instruments;General service targets should not be understood as individual case approval commitments。
Step 6:Be patient and wait for approvals and respond to inquiries
Respond to inquiries and supplementary information as required by the tax bureau。Processing time depends on organizational structure、Activity、Document completeness and query rounds;After being recognized, you must continue to meet charity and tax conditions。
5. List of documents required for application by Hong Kong S88 recognized charity organization
Main Form C.D.22 - Application for Confirmation of Tax Exemption Status Conferred by Section 88 of the Inland Revenue Ordinance
Attachment C.D.22A – Attachment to Application Form
Copy of company registration certificate (issued by Companies Registry)
Articles of Association (M&A) Official text (version approved by the Registrar of Companies)
Press C.D.22、C.D.22A and Applicant Instructions Provide Governing Organization Members、Authorized representatives and actual control arrangements, etc.;Proof of identity、Address and other personal information shall be subject to current forms and case requirements of the Inland Revenue Department.。
Provide activities carried out according to the current application form、Future event plans、Income and expenditure budget、Source of funds、Accounts and supporting documents;The required period and level of detail are subject to the establishment time of the organization and inquiries from the tax bureau.。
Detailed statement of the purpose of the organization
6. The absolute red line for applications by Hong Kong S88 recognized charitable organizations
political purpose:Political purposes themselves are generally not considered charitable purposes;Activities involving public policies or initiatives must be aligned with the organization’s stated purpose、Public interests and actual activities are judged on a case-by-case basis according to the tax bureau’s guidelines.,You can’t predict the outcome with just one sentence。
illegal activities:Organizations must comply with Hong Kong laws,and ensure that funds and activities are used for recognized charitable purposes。Facts that are illegal or inconsistent with charitable purposes may affect application or continued eligibility,The consequences will be handled by the competent authorities based on facts and laws.。
Pure commercial profit-making:The articles of incorporation include a request to the founders、Terms for distribution of profits to members,Never feasible。
For specific private groups:If you are only an employee of a company、A family member provides benefits,Not in the public interest。
Missing or illegal dissolution clauses:The remaining assets after dissolution must be donated to a charity with similar purposes and approved by section 88,Insufficient general expressions。
7. Frequently Asked Questions about Hong Kong S88 Recognized Charity Application
Regulatory instruments should generally prohibit governing members from obtaining benefits from the organization,However, the tax bureau’s example clauses allow for strict restrictions、Handling partial remuneration or service arrangements under conflict of interest procedures and reasonableness requirements。Can you pay、Who approves and required records must be in legal form、regulatory instruments、Inland Revenue Department guidance and confirmation of specific facts,It cannot be summarized as "absolute prohibition" or fixed three conditions。
Strictly implement the "declaration of conflicts of interest" clause in the charter。If the organization wants to lease a director’s property or purchase his company’s services,The director must fully disclose his or her interests to the board,Not allowed to participate in related discussions and voting,shall not be counted towards the quorum of the meeting。All transactions must be in the best interests of the institution,and have written records,Otherwise, you will face the risk of revocation of qualifications。
Can't。S88 license is tax status,Not equivalent to a public fundraising license。Charitable fundraisers or flag sales in public places,You must apply separately for the relevant license from the Social Welfare Department or the Home Affairs Department。
Never believe verbal claims。You should directly check the "List of Charitable Institutions and Charitable Trusts Exempted from Taxation under Section 88 of the Inland Revenue Ordinance" PDF document published on the official website of the Inland Revenue Department,This is the only official verification channel。
Description of the tax bureau’s current page:If the information submitted is sufficient and no further inquiries are required,We will try our best to reply within 4 months;This is not a guarantee of approval。Actual time still depends on architecture、regulatory instruments、Activity、Financial Information and Inquiry Rounds。
Article 88 Qualifications must continue to be met。Organizations should keep accounts、Activity and governance records,and provide information as required by the tax bureau;regulatory instruments、purpose、Activity、address、When there are major changes in governance or capital utilization,Declarations or re-confirmation requirements should be checked promptly。This page does not write "one month for all changes" as a unified legal time limit。
no。Only business profits directly carried out for charitable purposes are exempt from profits tax,and must meet the conditions:All profits go to charity、Not consumed in large quantities outside Hong Kong、The business is carried out to achieve charitable purposes。Profits generated from business activities unrelated to the purpose (such as investment property rentals) are still subject to tax。
Can。Newly established organizations are usually required to submit specific activity plans、Budget、Funding sources and governance arrangements,Let the tax bureau determine whether it is truly established and operated for charitable purposes。Whether activities should be carried out first must be decided on a case-by-case basis and legal advice,There is no uniform requirement that several events must be held first。
The most common one is that the articles of association do not contain mandatory provisions (such as irregular dissolution provisions)、The purpose does not meet the four major charitable purposes、File missing、Activity plan lacks substantial content,Or the institution is suspected of political purposes or profit distribution and other absolute red lines。
Hong Kong Huitong provides full-process application support for non-profit organizations,Including organizational structure planning、Drafting and revision of charter、Application document preparation and submission、Respond to Inland Revenue Department inquiries,and ongoing compliance consulting after accreditation。The application results and processing time are determined by the Hong Kong Inland Revenue Department on a case-by-case basis.。
Section 88 itself does not set out uniform professional qualifications for directors for all charities。Qualifications of Directors or Governance Officers、Liability and limitations depend on the legal form of the organization、Regulatory Instruments and Applicable Laws;When applying, you must also let the tax bureau understand the actual governance arrangements。
Can。company limited by guarantee、Different structures such as societies and trusts may apply,However, their establishment must be satisfied respectively、Governance and charitable purpose requirements。Member or trustee responsibilities should be compared、declare、audit、Asset holding and ongoing governance before selection。
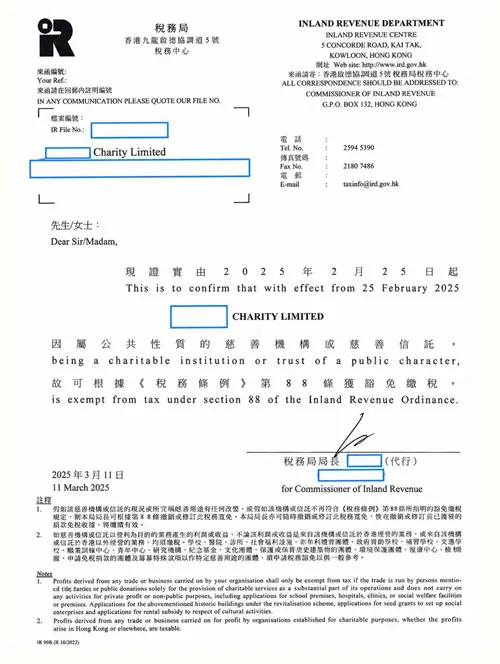
8. Article 88 Example of tax-exempt status confirmation document
9. Official verification points:S88 is a tax exemption qualification,Not a general business license
Section 88 of the Inland Revenue Ordinance relates to the qualifications for profits tax exemption of charities or charitable trusts;Whether an organization qualifies is determined by the tax bureau in accordance with its charter.、actual activities、Factual review of fund utilization and public interests,You cannot judge based on the company name or registration form alone。
Being recognized does not mean that all income is automatically tax-free。Business activities unrelated to charitable purposes、Purpose of funds or arrangement of assets,It still needs to be analyzed item by item according to the rules of the tax bureau.,and keep accounts、Activity and related transaction records。
Before applying, you should refer to the current application form and official instructions of the tax bureau.,Confirm the charitable purpose of the charter、Asset transfer and dissolution arrangements、Are governance and conflict of interest provisions consistent?;The fixed approval time limit mentioned in online articles should not be regarded as a case-by-case commitment。
public fundraising、flag sale、Street fundraising or other regulated fundraising activities,You may also need to apply for permission from the relevant government department;Article 88 tax qualifications are not a substitute for permission for these activities。
10. Relevant regulations、Regulatory information and further reading
| official information | Verification purpose |
|---|---|
| tax bureau:Section 88 Application、Forms and potential profits tax liability | legal nature、Application procedure、Conditional 4-month recovery target and business profit rules |
| Tax guide for charities and charitable trusts of a public nature | Charitable purposes、public interest、regulatory instruments、Governance and continuing obligations |
| Article 88 Charitable Institutions and Charitable Trust Inquiries | Check current name and tax-exempt status |
| Inland Revenue Department Section 88 List PDF | Official list download |

